
ClimeFi Announces New 85,000 Tonne Procurement Round
Published by Todd Bush on December 25, 2025
In its latest procurement round, ClimeFi has enabled more than US$18m in durable carbon removal purchases across eight removal pathways: Biochar, Bioenergy with Carbon Capture and Storage (BECCS), Direct Air Capture & Storage, Enhanced Rock Weathering, Microbial Carbon Removal, Mineralisation, Terrestrial Biomass Sequestration, and Wastewater Alkalinity Enhancement.
The total offtake commitments exceed 85,000 tCO₂, at an average price of US$213 per tonne.
>> In Other News: Alberta's First CCS Hub Just Started Injecting CO2
The suppliers retained in client portfolios include Andes, BioCirc, Carboneers, CREW Carbon, DeepSky, Exomad Green, Graphyte, InPlanet, O.C.O. Technologies, and Vaulted Deep.
The Process
The new purchases have been executed as part of a coordinated carbon removal procurement effort. Over the past six months, ClimeFi has aligned a number of carbon removal buyers, each pursuing ambitious sustainability strategies; by pooling demand, buyers were able to gain access to preferential terms and significant volume discounts. ClimeFi will announce the specific buyer-project collaborations in the coming weeks.
The chosen suppliers were confirmed following a thorough selection and due diligence process. In Q3 2025, ClimeFi ran a request for proposal (RFP) to help our clients get contextualised offers for their requirements. Following the review of a large number of submissions, projects distinguished by the overall quality, robustness, and transparency of their submissions – along with a credible minimum forecasted capacity of 20kt for the 2026–2030 period and strong alignment with our client portfolio – were selected for due diligence and offtake negotiations.
While successful in the initial procurement process, it is important to note that ClimeFi will continue to monitor these projects on an ongoing basis to assess and manage potential underlying project risks, including credit issuance delays and non-delivery risks.
Key Statistics From Our Purchases
Below, we present key statistics and data from our purchasing rounds, including the distribution of removal pathways, delivery years, CO₂ storage methods, and geographical location of the selected projects.
By pathway:
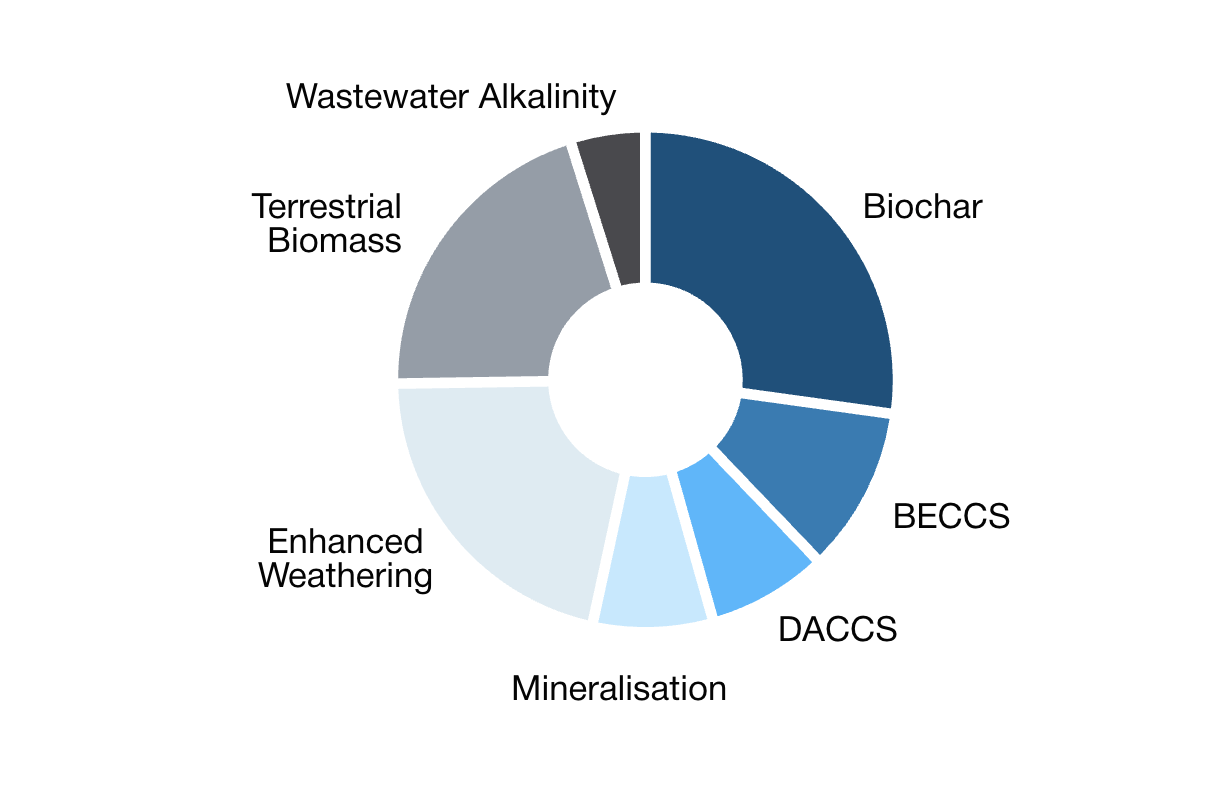
The purchasing cycle demonstrated significant market diversification spanning eight different removal pathways, highlighting a meaningful shift from reliance on a few carbon removal technologies to a much broader market landscape. Biochar took the majority share, with Enhanced Weathering and Terrestrial Biomass Sequestration following closely.
Figure 1: Volume commitment by pathways (% share of project)
By delivery vintage:
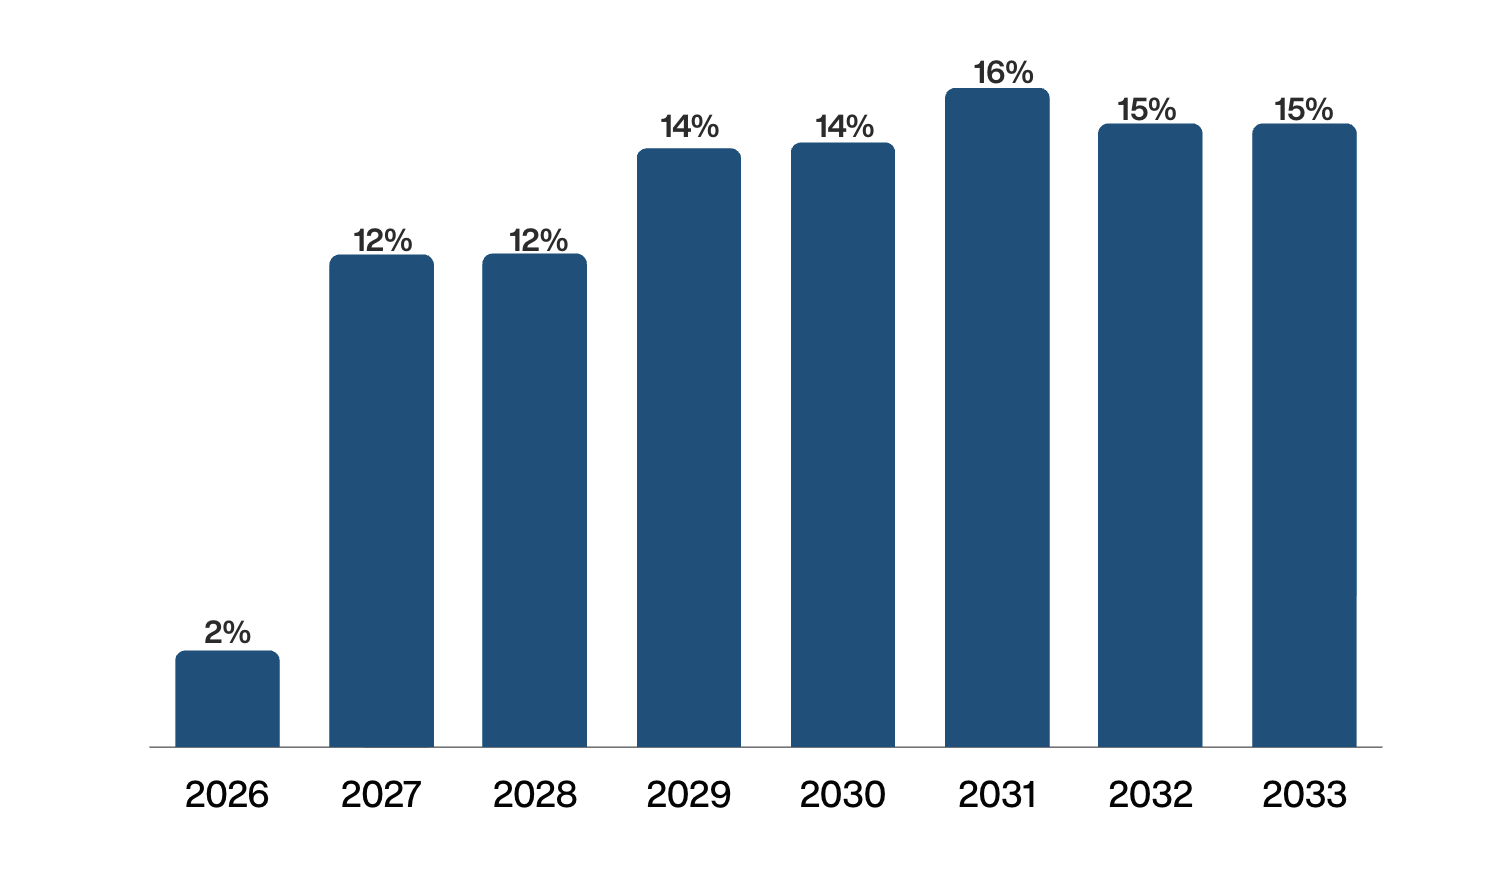
Total secured fixed volume commitments span 2026 to 2030 with the rising use of options through 2033, underlining ClimeFi’s commitment to long-term transactions. The majority of fixed volume commitments are due to be delivered in 2027 and 2028.
Figure 2: Total commitments by delivery year (% of total volume)
By geographical location:
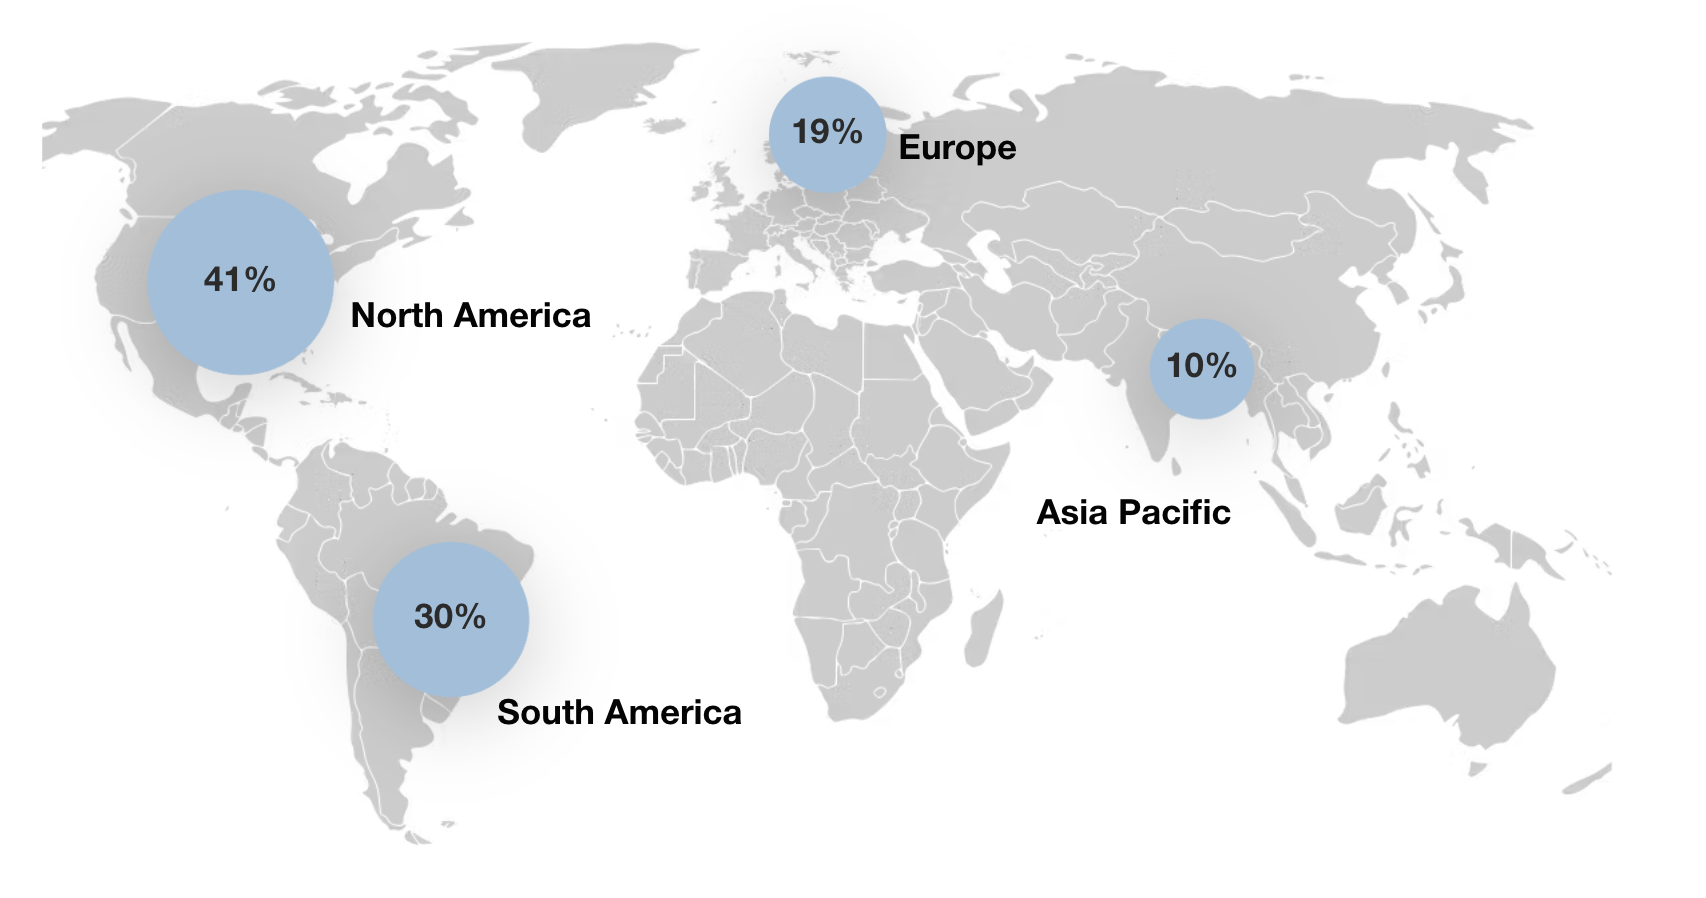
Purchases span four different continents, with 71% stemming from the Americas. This wide geographical split points to the growing appetite for durable carbon removal solutions around the world.
Figure 3: Fixed volume commitments by geography (% of total volume)
By storage method:
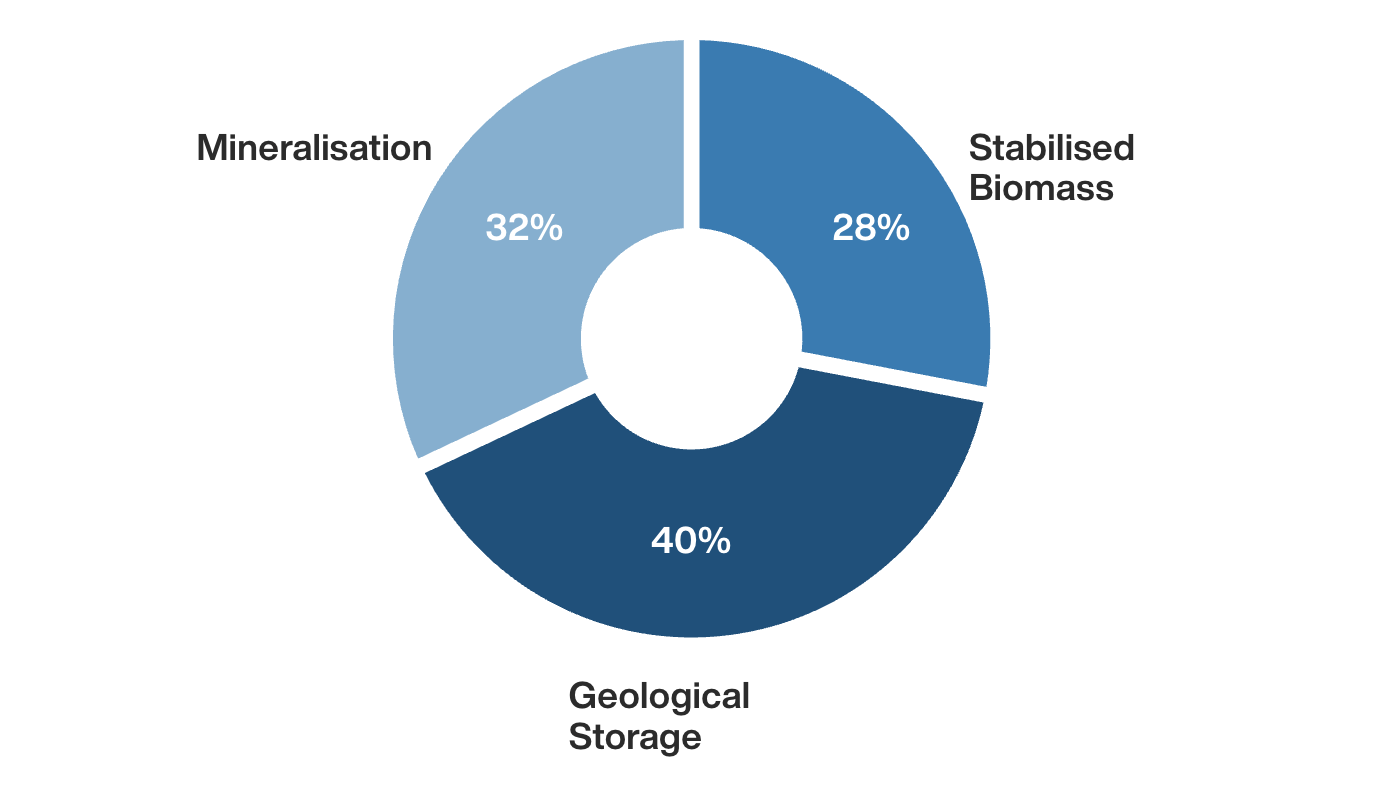
The purchases span three different storage methods: Stabilised Biomass, Mineralisation, and Geological Storage.
Figure 4: Fixed volume commitments by storage method (% of total volume)
Sebastien Dewarrat, Co-Founder at ClimeFi, said: “We are delighted to share the news of our latest procurement round publicly. ClimeFi is honoured to work hand-in-hand with a number of forward-thinking buyers on scaling durable carbon removal. We look forward to announcing the specific details of the collaborations in the coming months”.
Subscribe to the newsletter
Daily decarbonization data and news delivered to your inbox
Follow the money flow of climate, technology, and energy investments to uncover new opportunities and jobs.
Latest issues
-
113 CCS Projects: What's Driving the Surge?
Inside This Issue 🏭 Global CCS Hits 113 Projects as Americas Lead Capacity 💰 We're Moving $2M+ to Climate Solutions 💧 China Launches World's First Semi-submersible Offshore Wind-to-hydrogen Platfo...
-
Why Is Wyoming Giving 650,000 Acres to Carbon Storage?
Inside This Issue 🪨 Inside Blm's 650,000-Acre Bet on Wyoming Carbon Storage 🏭 California Advances Carbon Capture and Removal Regulations Under SB 905 ⚡ Why a Japanese Power Giant Is Betting on Den...
-
Colorado Joins the 7-State CCS Permit Fast Lane
Inside This Issue ⚖️ Colorado Takes Over Class VI Permits: What Changes for CCS? 🏭 Hebei Shoulang Facility Using LanzaTech Technology Achieves World’s First ISCC EU RCF Certification for Ethanol P...
Company Announcements
-
A consortium led by Novacium, together with Axel’One and AD-VENTA, has secured funding from the Defence Innovation Agency (AID) and the Directorate General of Armaments (DGA) under the RAPID progr...
-
Video: The Next Chapter https://youtu.be/LUIHqS35rMg Led by John Douglas, whose development experience includes the $8 billion Champlain Hudson Power Express, the collaboration brings major Nort...
-
Emvolon Raises $22 Million Funding Round to Launch Its Modular, Waste-to-Fuel Chemical Plants
Following its recent offtake agreement and increased commercial demand, Emvolon raises Series A and non-dilutive federal and state grants to launch first commercial system and adds industry growth ...
-
Puro.earth Expands DACCS Certification With CCS+ Methodologies
Puro.earth has published its CCS+ methodology documents, with direct air capture and geological storage (DACCS) as the first activity type implemented under its CCS+ Program. Puro.earth’s multi-pr...